
If you have worked for a few different companies over the years, you may have old group personal pension plans that you are no longer paying into and may not have looked at for some time. Many of these older pensions have lifestyle funds which automatically change how your money is invested as you get closer to the retirement age held on the plan. Depending on the plan, this can start several years before the selected retirement age, sometimes five or even ten years before.
The problem is that the retirement age on the plan may have been chosen a long time ago and may no longer reflect when you actually intend to retire. You may, for example, have selected age 60 when you joined the pension, but now expect to carry on working until 65 or 67. If the plan is still working towards age 60, it could have started moving your money into more cautious investments several years before that date. If you are then not planning to retire until 65 or 67, this could mean a significant period of time where your pension is invested more cautiously than you might want, potentially reducing the investment growth over that period.
Some older lifestyle funds were also designed at a time when buying an annuity at retirement was much more common. If that is not how you intend to take your pension now, the investment strategy may no longer fit with your plans. That does not mean there is anything wrong with the pension or that you necessarily need to move it. But if you have an old group personal pension from a previous employer that you have not looked at for some time, now could be a good time to review it.
Check the retirement age on the plan, how your money is invested and when any lifestyle changes are due to start. If your expected retirement age has changed, it is particularly important to check whether the investment strategy still fits with what you are planning to do. Leaving it until you are closer to retirement could mean the pension has already been moving into more cautious investments for several years. At Wingate Financial Planning, we can help you review old group personal pension plans from previous employers, understand how they are invested and whether they still fit with when and how you intend to retire.
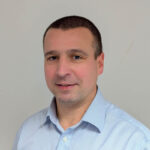
Paul Stevens | Financial Planning Adviser
Paul Stevens has over 30 years’ experience in financial services, including more than 26 years as an Independent Financial Adviser. He focuses on clear, practical advice and long-term client relationships, supporting individuals and families through every stage of their financial planning.